If you earn a salary in India, major social security changes just went into effect.
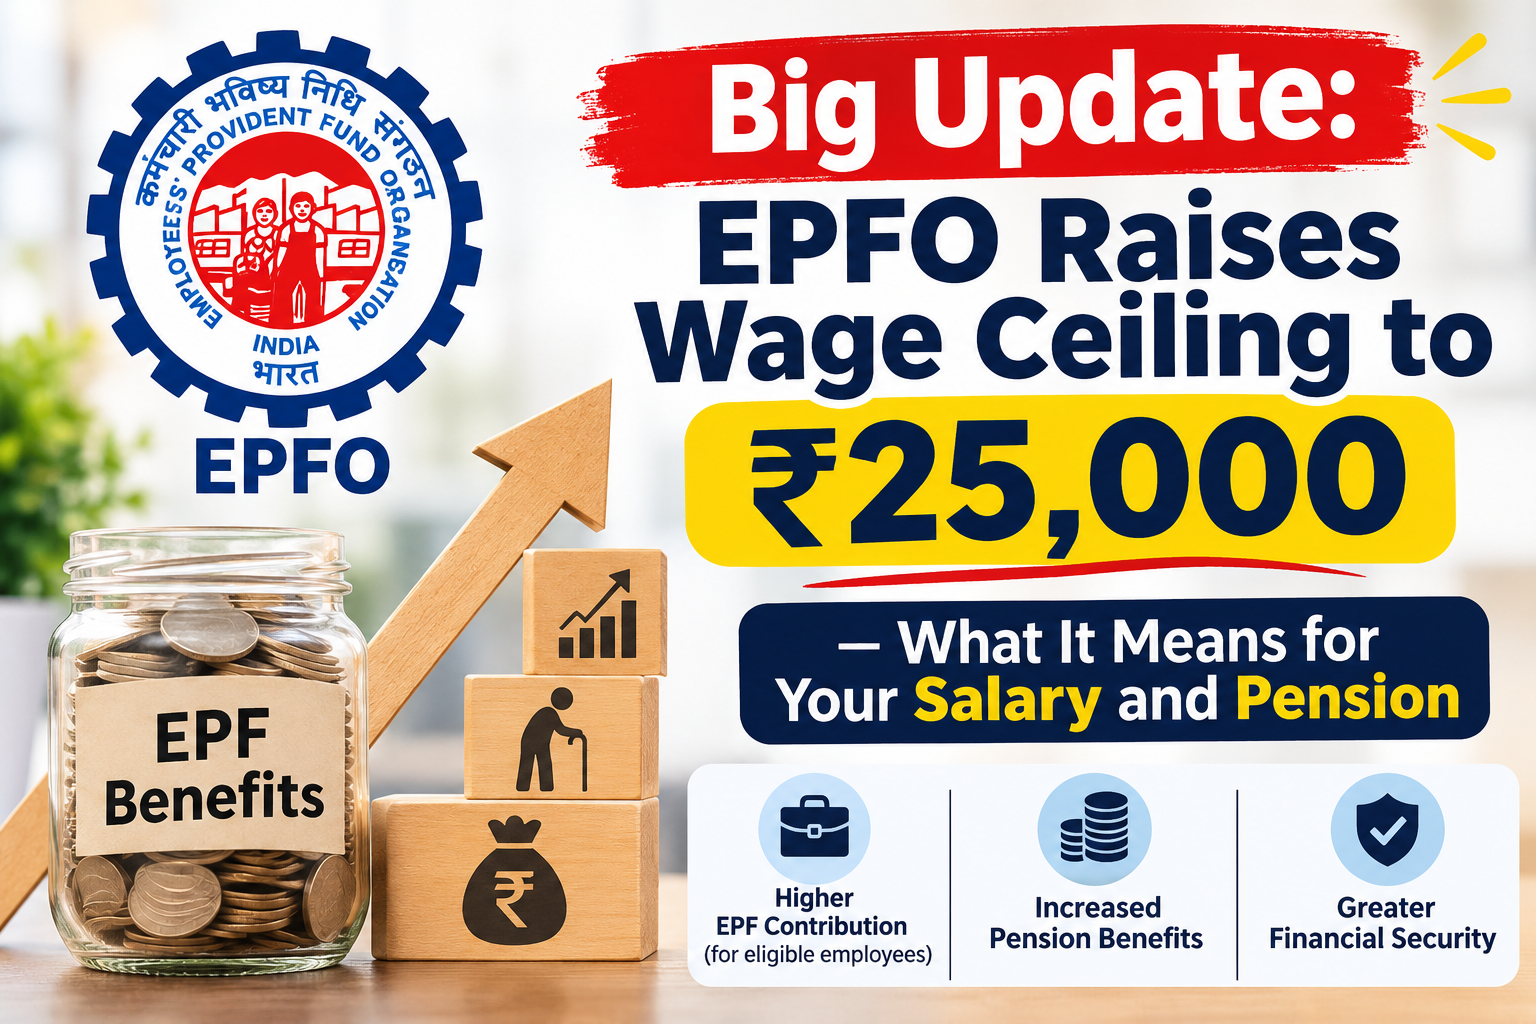
On September 17, 2026, the Ministry of Labour and Employment issued official Notification S.O. 5109(E) under the Code on Social Security, 2020. This notification officially raises the statutory EPFO wage ceiling from ₹15,000 per month to ₹25,000 per month.
Since the limit had been frozen at ₹15,000 since September 2014, this major policy update brings over 51 lakh additional employees into mandatory provident fund, pension, and insurance coverage.
Whether you are newly covered or an existing member, here is a clear breakdown of what has changed, how your salary is affected, and why this is a win for your long-term wealth.
What Has Changed? (At a Glance)
| Parameter | Old Rules (Up to Sept 16, 2026) | New Rules (From Sept 17, 2026) |
| Statutory EPF Wage Ceiling | ₹15,000 per month | ₹25,000 per month |
| Mandatory Coverage Threshold | Wages up to ₹15,000 | Wages up to ₹25,000 |
| Max Employee EPF Share (12%) | ₹1,800/month | ₹3,000/month |
| Max Employer EPS Pension Share (8.33%) | ₹1,250/month | ₹2,083/month |
| Max Employer EPF Share (3.67%) | ₹550/month | ₹917/month |
| Free Insurance Cover (EDLI @ 0.50%) | Capped at ₹75/month | Capped at ₹125/month |
How Does This Affect You?
1. If you earn between ₹15,001 and ₹25,000 and were NOT a PF member:
You are now mandatorily covered under EPF, EPS, and EDLI. Your employer will generate or link your Universal Account Number (UAN) with an official coverage start date of September 17, 2026.
2. If you are an existing PF member earning above ₹15,000 (restricted at ₹15,000):
Your PF wage cap automatically updates to ₹25,000 (or your actual wage, whichever is lower). Your monthly PF contribution will rise, which means higher matching contributions from your employer into your account.
3. If you earn above ₹25,000 and were never in PF:
You remain an “excluded employee,” but you can still join voluntarily if both you and your employer agree.
Will Your Take-Home Salary Decrease?
Because 12% of your wages (up to ₹25,000) will now go into your EPF account, your net take-home salary may see a minor reduction.
However, view this as shifting money from your “left pocket” (wallet) into your “right pocket” (high-yield savings account):
100% Matching Employer Money: Every rupee deducted from your salary is matched by your employer.
Compounding Interest: EPF offers attractive interest rates (8.25% p.a. for FY2025-26), compounded monthly.
Tax-Free Growth: EPF accumulations and interest grow tax-free under applicable IT rules.
Guaranteed Pension: Employer contributions up to 8.33% build a lifelong monthly pension (EPS) for your retirement, spouse, and dependents.
Free ₹7 Lakh Insurance: You receive automatic life insurance coverage (EDLI) up to ₹7,000,000 at zero cost to you (paid entirely by your employer).
Next Steps for Employees
- Check Your Pay Slip: Review your Basic + DA components in your upcoming pay slips.
- Verify UAN & KYC: Ensure your Aadhaar, PAN, and Bank details are updated on the EPFO Portal/UMANG App.
- Submit e-Nomination: Complete your e-Nomination online to secure immediate family pension and EDLI insurance rights.